
The AI coding bubble is two booms sharing a nickname. One is a stock and data-center build that Goldman Sachs still sizes at about $1 trillion worldwide in 2026. The other is the claim that coding agents have already turned extra keystrokes into extra finished software. The first boom can keep spending for months and still disappoint shareholders in 2027. The second one is already failing a simpler test: more code is landing, and the shipped work is not rising with it.
Humans who can tell a safe change from a plausible one are collecting the scarce payoff. Chip orders, bond deals, and model labs are collecting the capital. A $20 or $200 editor login sits in a third pile, and a bad week for Nvidia does not delete it.
The short answer on the AI coding bubble
A pop this week is the wrong forecast. Capital Economics told CNBC on 10 September 2026 that most of its bubble gauges say the equity boom is late, then still penciled in a higher S&P 500 by year-end 2026 (about 7,650 then, 8,250 by the close) and a fall to 6,500 by the end of 2027. That is roughly 8% up, then a 21% slide. James Reilly’s line was that, on past form, the end looks like months rather than years. Oxford Economics, on 29 September, put the painful part in the same window: the risks intensify as 2027 starts. A correction, in their wording, only needs results to miss elevated hopes. The technology can still be real.
For a working developer the useful split is elsewhere. In a Harvard study of 718 firms, AI coding agents lined up with 30% more lines of code, 20% more commits, and 23% more pull requests. Resolved tickets did not show a matching rise. Review time on those pull requests rose 49%. That is the bubble you can see in Git. It is a measurement problem with a bill attached.
Who benefits, if “AI” and “humans” are the two names in the question: owners of the buildout benefit while the capex is still being cheered, and they carry the debt if monetization misses. Companies that redesign work around experts are posting the large productivity gains. Developers who review, scope, and ship familiar code are the humans the labor data is still hiring. Early-career developers are the group absorbing the hiring damage. The model does not get a paycheck.
What is money Bubble?
Goldman Sachs Research, 7 August 2026, puts AI-related investment at about $1 trillion globally this year, including $581 billion in the United States. The bank’s cross-checks land near the same place: around $1 trillion worldwide and just under $600 billion in the US. Add the years since 2022 and the cumulative figure they use is $1.8 trillion by the end of 2026.
The commonly quoted hyperscaler capex number, $794 billion, is a messy shortcut. Goldman says it understates global AI capex by about $200 billion and overstates the US share by about $200 billion, because not every hyperscaler dollar is AI, a lot of the build sits outside the US, and private plus non-US spend gets left out. On their preferred series, US AI capex is 1.8% of GDP in 2026, 2.5% in 2027, and 2.8% in 2028. They also say the leading indicators they watch (chip-equipment imports, PMIs, GPU rental prices) are still near the top of their range since 2022, which is a way of saying the near-term spending tape still looks strong.
Oxford’s 29 September briefing is the cold shower on that tape. AI-related capex was an estimated 27% of US fixed investment in the second quarter, and cumulative investment in the sector topped 2% of US GDP across three years. In two centuries of tech booms, they say only the UK railway mania of the 1840s was a larger investment surge. Utilization-adjusted US productivity growth has been decelerating. AI firms are showing negative free cash flow. Consensus profit growth, in their view, does not line up with the productivity gains they think are likely. Dot-com at least produced measurable productivity quickly. This boom is being asked to do the same, soon.
The financing has changed shape since the summer notes. IMF managing director Kristalina Georgieva, 15 October 2026, wrote that hyperscalers’ share of investment-grade bond issuance rose more than tenfold in two years, from under 1% to 10%, and that the deals are often circular: hyperscalers invest in model labs, and the labs buy capacity from the same firms. The October 2026 Global Financial Stability Report says a disappointment in AI investment or profitability could cut global GDP, investment, and consumption by as much as 0.4%, 1.3%, and 0.6% by 2028. The same chapter notes that Bank of America’s August 2026 fund-manager survey ranked the “AI boom” as the top market risk. A background note puts interest expense in the second quarter of 2026 at nearly $6 billion across Alphabet, Amazon, Meta, Microsoft, and Oracle, more than double the year before, and records an Alphabet equity raise of about $85 billion in June 2026 (IMF background analysis).
Capital Economics, back on 10 September, still called leverage less alarming than earnings expectations, which were up at dot-com-peak territory, with index concentration in the same neighborhood. A month later the IMF put the debt and the circular funding in the foreground. I would not treat either shop as a calendar. I would treat the disagreement as the story: spending can stay huge and the equity still reprice, because the bust condition is “worse than the hope,” which is a low bar when the hope is a record.
Georgieva also offered the other half of Amara’s law in plain language. The short run gets overrated. The long run gets underrated. She put a possible growth boost on the order of half a percentage point a year over the next decade, and she was careful: businesses have to rebuild workflows before that shows up. About 40% of jobs globally are exposed to AI on IMF research, about 60% in advanced economies. She also said there is no apparent hit to the job market so far. Exposure is not a layoff count.
AI developer bubble review
The paper to read is Fiona Chen and James Stratton, “Artificial Intelligence in the Firm: Bottlenecks in Software Production”, Harvard, current version 4 August 2026. Jellyfish data: about 300 million work events, 725,938 workers, 718 firms, January 2021 through March 2026. Tools in the measurement include GitHub Copilot, Cursor, and Claude Code. Adoption of agents at these firms went from near zero in October 2024 to over 95% by January 2026.
Agents, after firm adoption:
| What moved | Change | Statistically solid? |
| Lines of code per worker | +30% (about 1,494 lines on a 5,017 baseline) | Yes |
| Commits per worker | +20% | Yes |
| Pull requests per worker | +23% | Yes |
| Jira issues resolved per worker | Point estimate about +3% (0.12 on a 3.67 baseline) | No |
| Days from pull request to merge | +49% (3.45 days on a 7.03-day baseline) | Yes |
| Pull requests with changes requested | Nearly doubled (about 13% to roughly 25%) | Yes |
| Comments per pull request | +35% (0.58 on a 1.66 baseline) | Yes |
| Share of workers who review | +14% | Yes |
| Overall employment | A zero they can measure; a drop bigger than 2.9% is ruled out | The drop is not there |
Assistants (Copilot and Cursor seats, before the agent wave) were milder: commits up a significant 9%, lines and pull requests up a little and not significant, review length basically flat.
I keep seeing a “12% more finished work” line in write-ups of this paper. That 12% is the gain the authors could rule out. Their confidence interval on agent-era issue completion stops at about 12% of the baseline. The estimate itself is a noisy few percent. Ars Technica’s October 2026 piece gets this right. Some summaries do not.
On time, the paper’s survey of 100 engineers put coding at about 30% of the week. The Jellyfish time imputation put it at 42%. The rest is review, planning, and the other work a ticket needs before it counts. By March 2026 nearly 80% of the firms had some AI in code review. Even then, 23.3% of review comments were from AI, and 10.8% of pull requests had at least one AI comment. Humans were still the review. One senior engineer they interviewed said the tools lack a grasp of what the feature is supposed to do. That matches the pile.
Bain’s 2026 Global Technology Report, as written up by CIO Dive on 2 October from a survey of nearly 300 senior technology leaders, is the manager version of the same gap. Developers complete about 21% more tasks. Time spent reviewing outputs is up 91%. Simultaneous workstreams are up 47%. Leaders say they expect a 95% productivity boost and a 148% faster release cycle within a year or two. What they say they are capturing now is 20% to 27%. Purna Doddapaneni’s line is the one worth keeping: the bottleneck moved from writing code to trusting it, and the system runs at the speed of the slowest human checkpoint.
Expectations at 95%, delivery around a quarter of that. If you want a bubble you can explain without a stock chart, it is that gap.
The 19% slowdown is a 2025 snapshot
METR’s randomized trial, published 10 July 2025, found 16 experienced open-source developers took 19% longer with early-2025 tools (mostly Cursor Pro and Claude 3.5 or 3.7 Sonnet) on 246 real issues in repos they already knew. Before the tasks they forecast a 24% speedup. Afterward they still believed they had been 20% faster. The 24 February 2026 update says the confidence interval on that slowdown ran from +2% to +39% longer.
METR then tried a later experiment and basically threw the clean read out. Developers were refusing to join if they had to work without AI. Pay had been cut from $150 an hour to $50. People running several agents at once made the clock meaningless. On the subset of original developers who came back, the raw estimate flipped to an 18% speedup, with an interval from 38% faster to 9% slower. New recruits came in around 4% faster, interval from 15% faster to 9% slower. METR’s own words: this is weak evidence, and the true speedup among people who opted out could be larger. They also say self-reported speed is still unreliable.
An earlier note on this site, the workflow piece, described that February update as a clean flip from 19% slower to 18% faster. The note from METR is narrower than that sentence. Use the 2025 result as history. Use the 2026 result as “the lab can no longer run the old experiment, because too many developers will not work naked.” That refusal is a fact about adoption. It is a poor fact about how many minutes you saved on Tuesday.
What developers themselves trust
Stack Overflow’s 2026 survey is the mood, not a stopwatch. Among people using coding assistants or agents, 73% use them daily, and 30.9% of daily AI users are on the tools four hours or more. Trust is conditional: 48% trust the output when they can check it, and 16% extend trust to most tasks that are not important decisions. The work they actually hand over is familiar code (69.3%), debugging or refactoring (63.8%), straight technical questions (59.4%), tests (58.1%), and unfamiliar code (56.0%).
Among people who had used a coding agent or assistant in the past year (n = 12,255), Claude Code was 65.5%, GitHub Copilot 58.7%, OpenAI Codex 29.5%, and Cursor 25.5%. Multi-select, so the shares overlap. Only 6.4% said they switched tools for a lower price. Better output was the reason for 25.1%. The seat market is not behaving like a bubble that already popped. It is behaving like a quality fight.
17.1% said they avoid AI at work because they worry about losing the skill, or about training a replacement. That lines up with the skill-atrophy problem already on this site. The other 41.3% said they do not avoid it. Both groups are in the same profession.
Who benefits
AI versus humans” is a bad scoreboard. AI does not invoice. These are the parties that do.
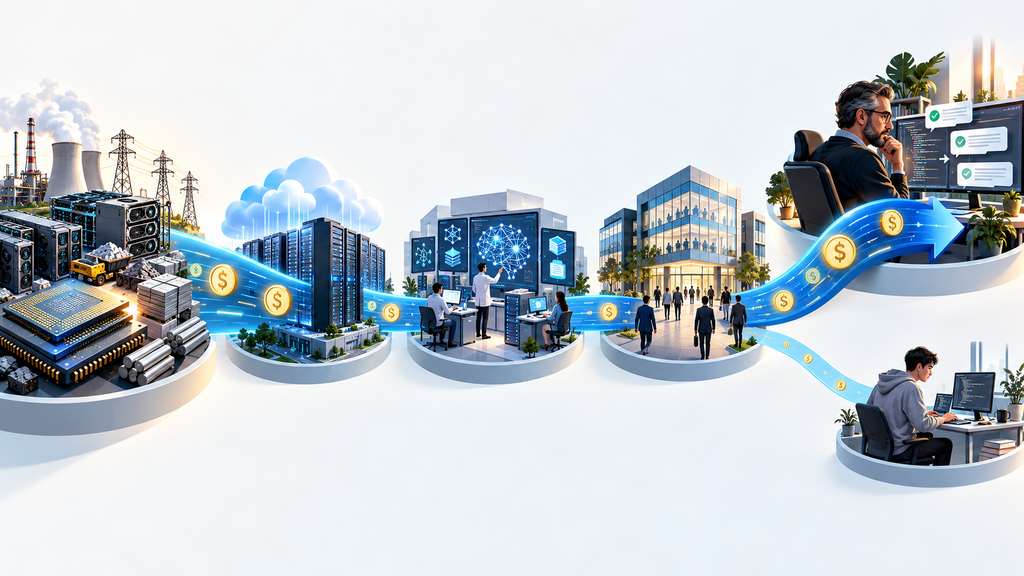
| Who | What they are getting, late 2026 | What a 2027 repricing changes |
| Chip, memory, and power suppliers | Orders inside a $1 trillion build | Volumes cool if capex growth slows. Goldman’s own indicators say that slowdown is not here yet. |
| Hyperscalers (Alphabet, Amazon, Meta, Microsoft, plus Oracle in the IMF interest cut) | Capacity, and a bond share that went from under 1% to 10%. Interest expense near $6 billion in one quarter across the five. | Equity and funding cost. The core businesses are still profitable. The free-cash-flow story is the stressed part. |
| Model labs | Usage, and circular capacity deals with the same hyperscalers | A harder fundraise, and pressure on API prices, if earnings miss the hope |
| Employers who redesign around experts | PwC, 15 June 2026: the top 20% of the most AI-exposed companies, 163% labor-productivity growth versus 2018. The most exposed group overall, 34%. The least exposed, 24%. | They keep the operating system. Seat counts get audited. The workflow stays. |
| Employers who bought seats and a headcount story | More pull requests, a 49% longer review, employment in the Harvard sample basically unchanged | These are the accounts that cancel the duplicate agent first. See also the layoff-and-rehire pattern. |
| Developers who can review and ship | Indeed Hiring Lab, via CNBC on 11 October 2026: US software-development postings up nearly 15% since February 2025, while postings overall fell 7%. Senior roles were 71% of the May 2025–May 2026 increase. AI-titled jobs were 37% of it. Postings are still about 27.5% under the pre-pandemic level. | A market dip does not remove the review job. It can freeze the req. |
| Early-career developers | Same CNBC report, citing Stanford’s 2026 AI Index: employment for ages 22 to 25 in AI-exposed fields down 16% since generative AI took off; early-career software developers down 20%. PwC, on 2.4 million US entry-level ads: roles most exposed to AI are seven times as likely to demand senior-style judgment. Those “seniorised” openings grew 35% since 2019. Other entry-level openings fell 10%. | The apprenticeship tasks are the ones the agent drafts. The hiring bar moved up. |
| A single developer’s subscription | A tool you can verify on familiar code. Stack Overflow: cost was why 6.4% switched. | Almost nothing, until a vendor reprices, rate-limits, or your finance team asks which seat closed a ticket. |
PwC’s wage split is the cleanest “which humans” number in the set. On more than a billion job ads, roles they class as professionalised (AI takes the routine slice, the human keeps judgment) grew available jobs twice as fast as democratised roles, with 42% faster salary growth. Headcount at the most AI-exposed companies rose 52% from a 2018 baseline, versus 36% at the least exposed, and wages 24% versus 17%. Jobs asking for specific AI skills grew 69%, against 9% for the job market, and the wage premium for those skills was 62%.
Read that next to Harvard, or you will fool yourself. Inside firms that adopted coding agents, Chen and Stratton could not pin a junior-versus-senior employment change on the rollout, and they could not pin a company-wide jobs cut on it either. They flag the limits: short run, partial equilibrium, one analytics vendor’s customers. A company can roll out Claude Code and keep its juniors, while the wider market stops opening junior reqs. CNBC’s 11 October labor piece is that second picture. The BLS projection they cite still has software-developer employment growing 10% from 2025 to 2035, from about 1.72 million jobs to 1.89 million. The profession is not the bubble. The easy on-ramp is.
My own cut, after sitting with both: the humans who benefit are the ones who can close the review, name the tradeoff, and talk to the user. The humans who lose ground are the ones whose practice used to be the first draft. Companies benefit when they spend the saved drafting on a product somebody will pay for. They waste the seat when the only scoreboard is lines of code. That is an unglamorous answer, and it fits the tables better than “AI wins” or “humans win.”
What to keep paying
Pay for one coding agent you already trust on a repo you know. The October comparison on this site still has the practical split: Claude Code when the hard part is a multi-file change, Cursor when the editor itself is the product you want, GitHub Copilot when the team’s pull requests already live on GitHub and finance wants one Microsoft seat. What those tools cost once you leave the sticker price is a separate decision from a CNBC chyron.
Do not buy the top lane twice because the timeline feels loud. The Max versus Ultra piece, prices checked 21 October 2026, is the wallet version: both $200 seats exist, and most people who think they need both have not shown that a cheaper pair fails. Recheck the vendor pages before you renew. Limits move.
| Your week looks like this | Keep | Drop or pause |
| You can check the diff on code you already understand | One main agent | A second and third seat opened “so we have options” |
| Pull requests are up, merged issues are flat, review comments are multiplying | Reviewer time, tests, a written bar for what “done” means | Another agent bought to outrun the queue |
| The company is already a GitHub shop | The shared Copilot seat | A personal top-tier plan nobody will reimburse |
| You are early in your career | The tool, plus reading every diff before you accept it | Using the agent as the only reps you get |
| Finance wants an AI cut because of a bubble headline | The seat you can tie to issues closed | The duplicate, and any spend you can only defend with lines of code |
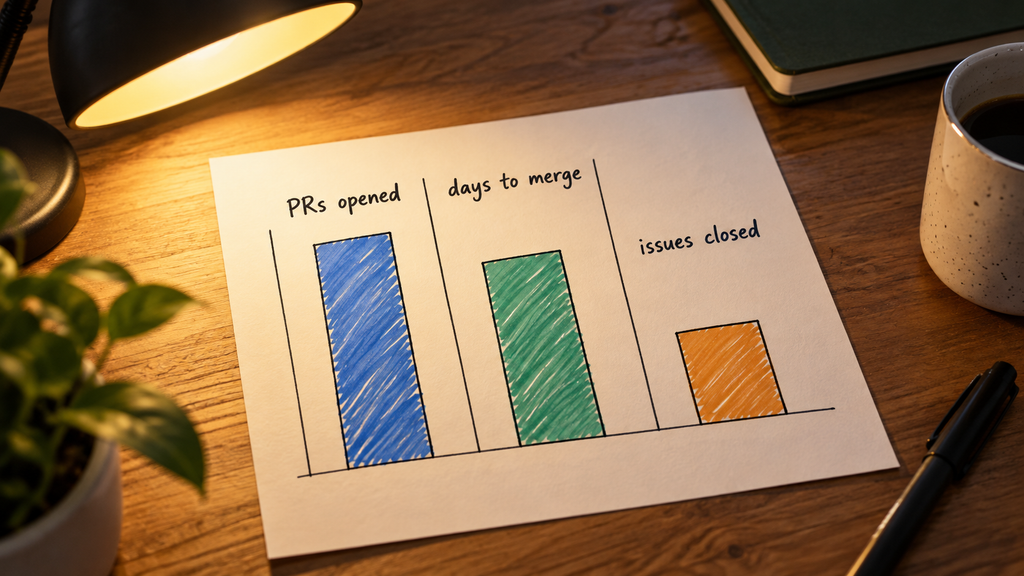
A two-week log is enough to know which row you are in. Count pull requests opened, days until merge, and issues actually closed. If the first number rises and the third one does not, you are living the Harvard result in miniature. Bring that log to the budget meeting. “We might be in a bubble” is not a measurement.
Where people fib to themselves
Lines of code are a vanity metric the moment an agent is in the repo. Chen and Stratton’s whole point is that the intermediate count and the shipped count come apart. If your dashboard leads with accept-rate or LOC, you are scoring the boom, not the work. The maintenance version of that fib is AI technical debt: code that passes and still costs a senior a week six months later.
The 12% figure will keep circulating. If a vendor slide uses it as “agents increase output 12%,” ask whether they mean the confidence-interval ceiling. They usually do not know.
The July 2025 METR slowdown will also keep circulating, sometimes from this site’s older wording. It described early-2025 tools on experienced maintainers. METR has said the follow-up cannot support a clean current percentage. Quote them, or leave the percentage out.
A stock drop is not a product sunset. Georgieva’s scenario is an equity and spending shock amplified by leverage and circular deals. Your editor keeps working the next morning. The way a correction reaches a developer is a renewal email, a tighter rate limit, or a finance partner who suddenly wants one seat instead of three. Have the log before that email.
And the reverse fib, “the agent deleted the job,” is also sloppy. Harvard’s adopters did not show that employment drop. Indeed’s postings rebounded, concentrated in senior and AI-titled roles. The documented human damage is the narrower one: fewer easy openings for the youngest developers, and a review load shifted onto people who already know the system. The code-review piece is what that load feels like on a Tuesday.
A full pop before year-end is not the base case of the notes checked for this piece. Capital Economics, via CNBC on 10 September 2026, still had the S&P 500 higher by the end of 2026 and lower by the end of 2027, down to 6,500 from a path that topped out near 8,250. Oxford Economics said the correction risks intensify entering 2027. The IMF’s October report treats a disappointment in AI profits or spending as a real financial-stability risk, made worse by leverage, without dating a crash to this quarter. Spending forecasts from Goldman, as of 7 August, still look strong in the near term.
Companies that use AI to extend expert work are showing the large gains: PwC’s top fifth of the most AI-exposed firms, 163% labor-productivity growth versus 2018. Humans benefit unevenly. Professionalised roles, where judgment stays with the person, have faster job growth and 42% faster salary growth than roles AI makes easier for a non-expert. Senior software-development postings drove 71% of the recent US rebound Indeed reported. Early-career software developers are the weak side of the same market. The model is a cost. Its owners and its power bill are the capital beneficiaries, and they are the ones borrowing to keep the build going.
They made coding activity faster in the Harvard-Jellyfish sample: 30% more lines, 20% more commits, 23% more pull requests after agent adoption. They did not produce a statistically significant rise in resolved Jira issues or epics. Review time rose 49%, change requests nearly doubled, and comments per pull request rose 35%. Bain’s survey of technology leaders found about 21% more tasks completed and 91% more time reviewing. Faster drafting is real. Faster delivery is the part that fails to show up.
Cancel a duplicate seat you cannot tie to closed work. Keep one agent you can check. Stack Overflow’s 2026 respondents mostly switch tools for better output (25.1%), not for price (6.4%). A market correction hits hyperscaler valuations and capex plans first. It reaches a developer as a renewal, a rate limit, or a budget review. Measure pull requests, merge time, and issues closed for two weeks so that review has a number.
Which developers are gaining from AI?
People who already know the codebase well enough to verify output. That is where Stack Overflow respondents actually use the tools: 69.3% on familiar code, 63.8% on debugging and refactoring. Labor-market data points the same way. Senior roles accounted for most of the recent rise in US software-development postings, and PwC finds faster wage growth where AI professionalises a job instead of deskilling it. Juniors gain speed on drafts and lose the reps those drafts used to provide. Seventeen percent of survey respondents already avoid AI because of that skill worry.
It is the gap between what the spending and the demos imply and what the production numbers show. Goldman’s build is about $1 trillion this year. Leaders in Bain’s survey hope for a 95% productivity jump and report something closer to 20–27% captured. Harvard’s agents raise code volume by about a third and do not raise shipped issues in a way the study can separate from noise. The technology can keep improving. The bubble is the habit of paying, hiring, and forecasting as if the review bottleneck had already disappeared.
The next step is dull on purpose. Pick the one seat in the Claude Code, Cursor, and Copilot comparison, run the two-week count, and keep the receipt. If 2027 reprices the stocks, you will still need a human who can merge. The posts on review load, what the seats cost, and which $200 plan is the redundant one are the practical follow-ons. The equity story can burst on a calendar you do not control. The review queue is already on yours.